Finance a snack vending machine: monthly instalments instead of one payment
Financing spreads the investment in your vending machine over predictable monthly instalments, and after the last instalment the machine is yours. This keeps financial headroom for business founders, side-business operators and established companies.
After the last instalment the machine is yours
Predictable monthly instalments
Also for business founders & side businesses
For entrepreneurs (§ 14 BGB)
Why finance a snack vending machine?
Depending on its equipment, a vending machine costs several thousand euros. Financing spreads the investment over fixed monthly instalments while you are already operating the machine.
Protect liquidity: predictable monthly instalments keep capital in the business
Predictable: a fixed monthly instalment over the chosen term (usually 24–60 months)
Clear contractual basis: term and instalment are set out in the individual offer
Start operating as soon as the machine is delivered
SnackDragon sells exclusively to entrepreneurs (§ 14 BGB). Financing is provided by a specialised partner; your actual monthly instalment depends on the model, term, credit check and individual offer.
How financing works
Financing runs through our financing partner. You pay a fixed monthly instalment over the chosen term.
Term
24, 36, 48 or 60 months. The instalment stays the same over the entire term and can be planned firmly.
Ownership
After the last instalment the machine is yours. The exact conditions are set out in the individual offer.
How financing and buying differ for tax purposes
The decision often depends less on the size of the instalment than on how both options affect your accounts and liquidity. The basics:
Financing
Economically a purchase in instalments: you capitalise the machine from the start and depreciate it. Only the interest portion of the instalment is an operating expense, not the repayment. You pay the VAT on the sum of all instalments with the first instalment; if you are entitled to deduct input VAT, you reclaim it from the tax office.
Purchase
You capitalise the machine and depreciate it over its useful life. The purchase price therefore does not reduce profit immediately but is spread over several years.
The official German depreciation table (AfA table) of the Federal Ministry of Finance sets a standard useful life of 5 years for vending machines. For a TCN-CSC-10C(V22) in premium full equipment with NV11 and DCM5, without the optional extension connection, at 5,474 € net, that is about 1,095 € depreciation per year (this figure applies equally to purchase and financing).
This is guidance, not tax advice. How financing or buying works out in your case depends on how you determine your profit, your entitlement to deduct input VAT and the specific contract. Agree the approach with your tax adviser before signing.
Who financing pays off for in particular
Especially when entering the vending business, financing reduces the capital needed up front. The monthly instalment can be built firmly into your ongoing planning.
Business founders and young companies: get started with a predictable capital outlay
Side business / side hustle: plan your first machine with monthly instalments
Existing operators: expand to further locations while keeping financial headroom
Property managers, offices, gyms: finance on-site supply in a predictable way
How financing works
The process is lean and runs alongside choosing the machine. The credit check and the contract are handled by the financing partner; we deliver the machine.
Choose the machine and configuration (model, payment technology, accessories)
Request financing (with your preferred term and a few company details)
The partner checks creditworthiness and makes a specific instalment offer
Financing agreement between you and the financing partner
We deliver the machine and you start operating
Which machines can be financed
Financing can be requested for all our vending machines. Approval and conditions come with the individual offer from the financing partner.
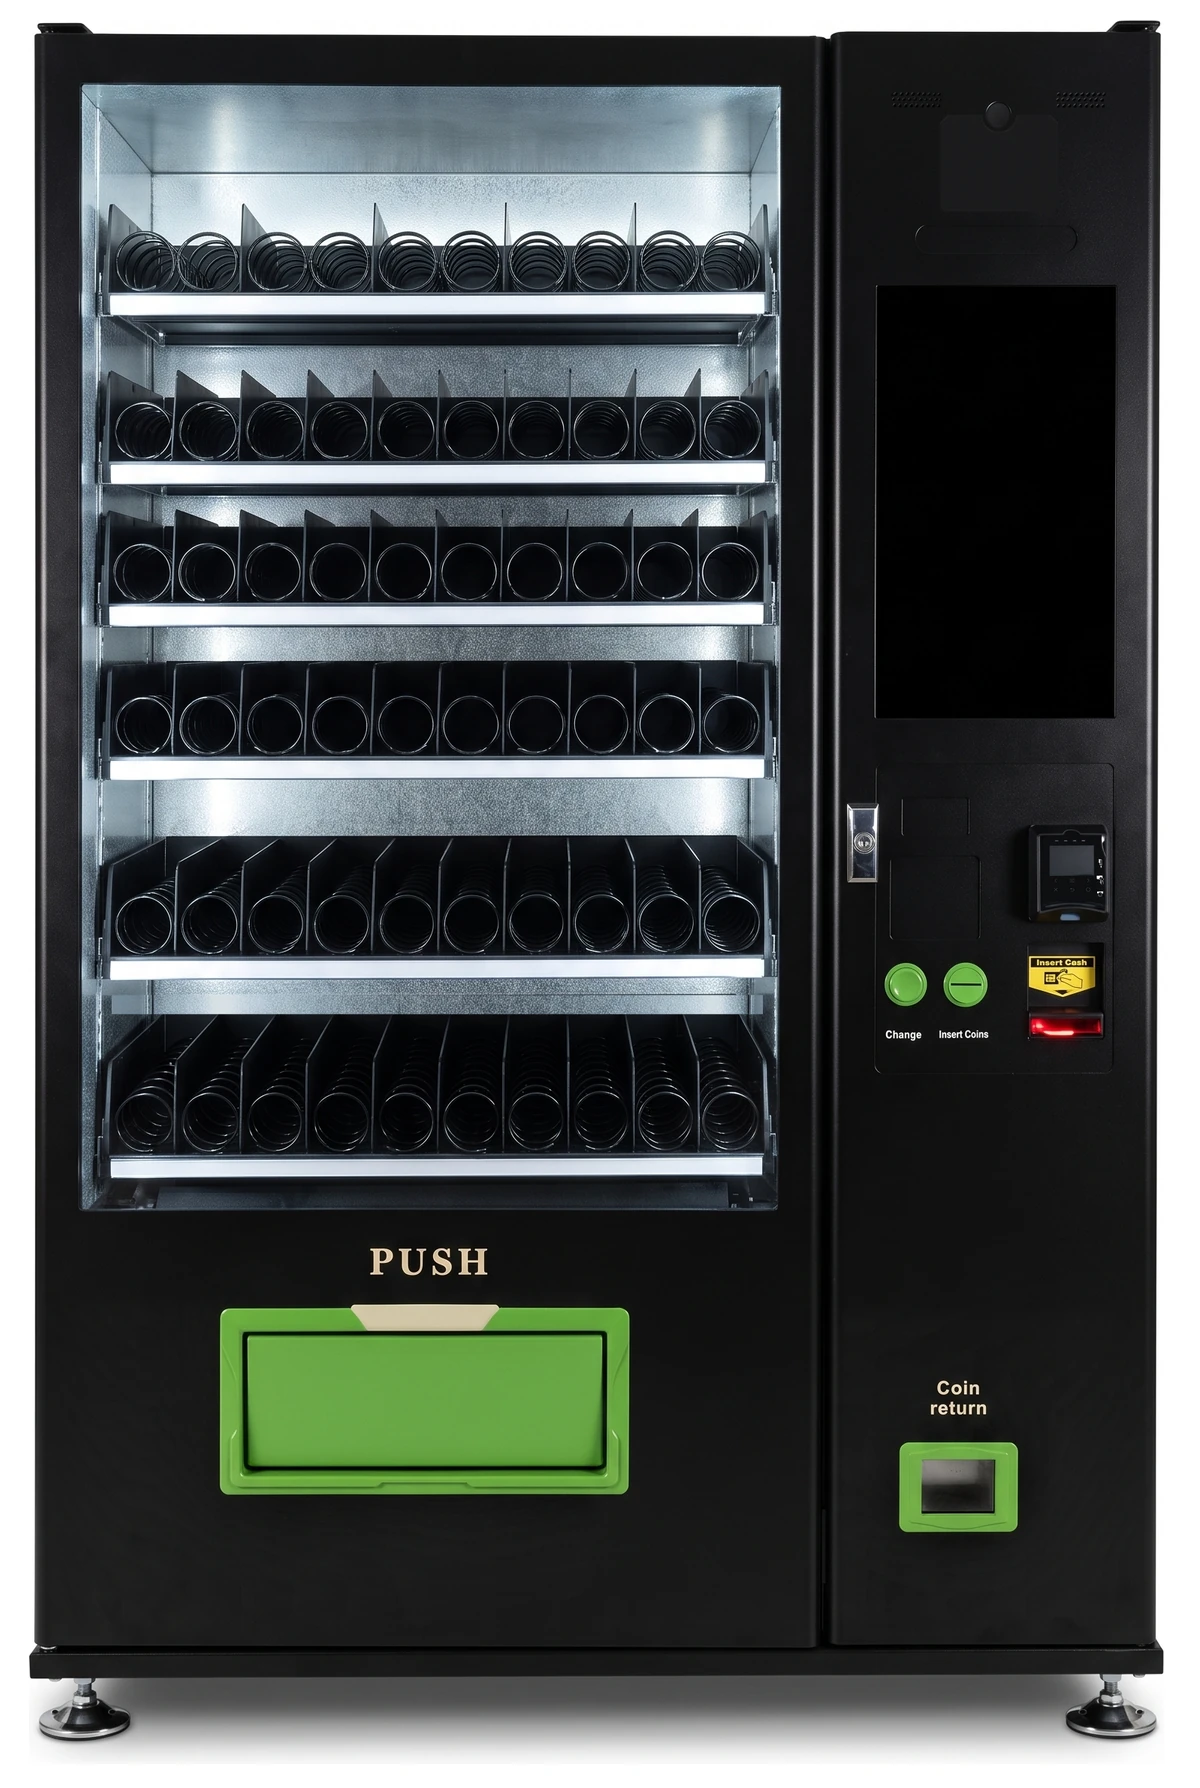
Snack and drink machine with gentle lift delivery for delicate products.
Financing from 135.30 € net per month
Example calculation over a 60-month term based on the net price of the standard equipment. The amount is a non-binding indication, subject to a credit check; additional equipment increases the instalment.
Frequently asked questions about financing
Can I lease a snack vending machine instead of buying it?
We offer financing instead: fixed monthly instalments, and after the last instalment the machine is yours. Business customers can request it without obligation; conditions and approval follow after a credit check in the individual offer.
Is financing also possible for business founders and side businesses?
Yes. Young businesses and side-business founders can also request financing. The partner names the documents needed in each case directly during the request process.
Which terms are possible?
Terms of 24, 36, 48 or 60 months are possible. The actual monthly instalment depends on the model, term and creditworthiness.
Which machines does financing apply to?
In principle to all our vending machines: the TCN-CSC-10C(V22), the TCN-CSC-10N, the TCN-D900-9C(V22) and the TCN-CEL-10C(V22). We clarify which model suits your location in the request.
Request financing
Submit a non-binding financing request. You choose the preferred model and term, and we pass the request on to our financing partner. You receive a specific monthly instalment after review and offer.
Non-binding financing request for business customers. Conditions and approval follow after a credit check in the binding offer from the financing partner.